Direct Express Mortgage
Live in one. Rent the others. Lower your cost of living.
Your first home could also be the start of your rental portfolio. Buy a duplex, triplex or fourplex, live in one unit and rent the others to offset your housing costs, while every payment pays down principal and builds equity. Some owners live there a couple of years, then rent the whole property, subject to occupancy and loan requirements. Direct Express helps you compare the property, financing, rental income and expenses to see what you would actually pay each month.
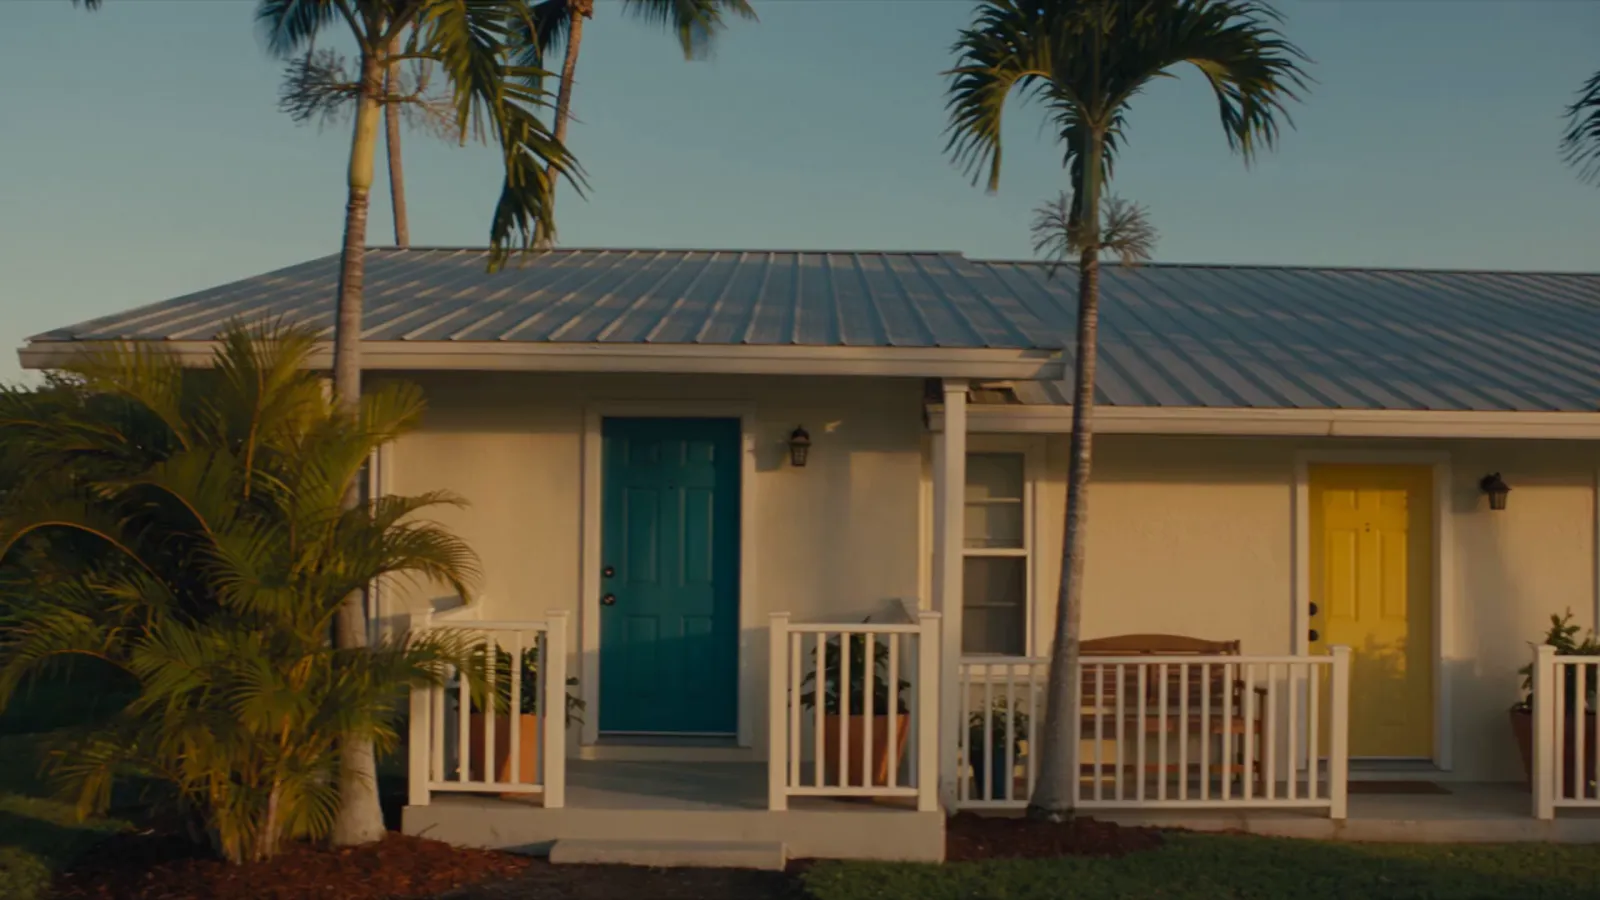
Film: Florida multi-unit home with separate front doors and porches. Illustrative.
What gets reviewed
Questions to answer before you buy.
- You must live in one unit as your primary residence
- Loan limits depend on the county and the number of units
- Three and four unit properties have an additional rental self-sufficiency test
- Rental income used to qualify must meet documentation rules
- Budget for vacancy, repairs, taxes, insurance and mortgage insurance
- Get thorough inspections and review the major systems (roof, HVAC, water heaters, plumbing, electrical) and likely replacements over the next five to seven years; use the findings to discuss repairs or negotiate terms
How it works
One unit is home. The others may help.
Choose a property size to see how an owner-occupied FHA purchase is laid out.
- You live in unit 1. The other 3 units are rented, and that rent may help cover the mortgage.
- You live in one unit as your primary residence
- The other units can be rented
- Rental income may help you qualify, if it meets documentation rules
- Three and four unit properties also face a rental self-sufficiency test
- With 4 units, the rental self-sufficiency test applies.
Illustration only. Loan limits depend on the county and the number of units, and every loan is subject to program guidelines and lender approval. 3D model is illustrative.
Sample purchase breakdown
Duplex and triplex: cash to close and the first payment.
Each example is calculated from its own financed balance. The buyer lives in one unit; only the other units count as rent collected.
Illustrative terms dated November 17, 2026 · 6.75% fixed rate, estimated 7.58% APR, 30 years · assumed 680 credit score
Duplex — two units, $360,000
- 3.5% down payment
- $12,600
- Estimated closing costs and prepaids (3%)
- $10,800
- Negotiated seller credit assumed (3%)
- −$10,800
- Estimated buyer cash to close, before deposit credit
- $12,600
- Base loan
- $347,400
- Financed 1.75% FHA upfront mortgage insurance
- $6,079.50
- Total starting loan
- $353,479.50
- Monthly principal and interest
- $2,292.66
- First payment toward principal (equity)
- $304.34
- First payment toward interest
- $1,988.32
- Rent collected: 1 unit × $1,600
- $1,600/mo
Triplex — three units, $500,000
- 3.5% down payment
- $17,500
- Estimated closing costs and prepaids (3%)
- $15,000
- Negotiated seller credit assumed (3%)
- −$15,000
- Estimated buyer cash to close, before deposit credit
- $17,500
- Base loan
- $482,500
- Financed 1.75% FHA upfront mortgage insurance
- $8,443.75
- Total starting loan
- $490,943.75
- Monthly principal and interest
- $3,184.25
- First payment toward principal (equity)
- $422.69
- First payment toward interest
- $2,761.56
- Balance paid down after 12 payments (equity built, not cash received)
- ≈$5,232
- Rent collected: 2 units × $1,600
- $3,200/mo
Cash-to-close estimates assume the property appraises for at least the price and the seller agrees to cover the eligible closing costs and prepaids shown. FHA allows interested-party contributions up to 6% of the sale price toward eligible costs, limited to actual permitted charges. The buyer supplies the down payment and any uncovered costs.
Illustrative only, not an offer of credit or a rate quote. 6.75% interest rate; estimated annual percentage rate (APR) 7.58%, which includes the financed 1.75% upfront FHA mortgage insurance premium, monthly FHA mortgage insurance at 0.55% a year and assumed lender fees of 1% of the loan. 360 monthly principal and interest payments of $2,292.66 (duplex) or $3,184.25 (triplex). Taxes, insurance and monthly FHA mortgage insurance are not included in those payments and increase the actual payment; see the full payment below. Your rate, APR and fees depend on your credit, the property and the lender, and are shown on a written Loan Estimate. Direct Express Mortgage NMLS # 1171053.
Monthly housing payment less scheduled rental income
Market rent vs. what the other units can cover.
Full monthly payment, itemized, minus only the rent from the units you don’t live in.
Illustrative example · assumptions only
Duplex
- Principal and interest
- $2,292.66
- Property taxes (est. 1.7% of price ÷ 12)
- $510.00
- Property insurance (estimate)
- $350.00
- Monthly FHA mortgage insurance (0.55% of base loan ÷ 12)
- $159.22
- Full monthly housing payment
- $3,311.88
- Less rent collected (1 unit)
- −$1,600.00
- Housing payment less scheduled rental income
- $1,711.88
Triplex
- Principal and interest
- $3,184.25
- Property taxes (est. 1.7% of price ÷ 12)
- $708.33
- Property insurance (estimate)
- $450.00
- Monthly FHA mortgage insurance (0.55% of base loan ÷ 12)
- $221.15
- Full monthly housing payment
- $4,563.73
- Less rent collected (2 units)
- −$3,200.00
- Housing payment less scheduled rental income
- $1,363.73
Duplex: what it costs you to live there
- Mortgage (principal and interest) minus rent collected
- $692.66
- Your full monthly cost after rent, with taxes, insurance and mortgage insurance
- $1,711.88
- Of that, paid toward your own loan balance in month one (equity you keep)
- $304.34
- Renting a similar unit instead (assumed)
- $1,600.00
- Compared with renting
- About $112 more a month, and you own the building
Triplex: what it costs you to live there
- Mortgage (principal and interest) minus rent collected
- −$15.75 (rent covers it)
- Your full monthly cost after rent, with taxes, insurance and mortgage insurance
- $1,363.73
- Of that, paid toward your own loan balance in month one (equity you keep)
- $422.69
- Renting a similar unit instead (assumed)
- $1,600.00
- Compared with renting
- About $236 less a month, and you own the building
These figures exclude vacancy, maintenance and capital replacements. Taxes and insurance are placeholders until verified for a specific property.
Rent from the other units offsets what you pay; it does not lower the mortgage payment you owe. The full payment is due every month whether or not the units are rented.
Illustrative only. Every figure is an assumption for demonstration, not an offer of credit or a promise of savings.
Three- and four-unit purchases
Cash to close plus required reserves.
FHA requires three months of principal, interest, taxes and insurance (PITI) to remain in eligible, verified bank, investment or retirement assets after you pay the down payment and closing costs.
Illustrative example · assumptions only
Triplex example
- Estimated cash to close
- $17,500
- Required reserves: 3 × PITI of $4,342.58
- $13,027.74
- Total funds to document
- $30,527.74
Quick reference
- PITI of $3,500 → reserves
- $10,500
- PITI of $4,000 → reserves
- $12,000
Rental self-sufficiency (3 and 4 units): FHA takes the appraiser’s rents for all units, including yours, less the greater of the appraiser’s vacancy and maintenance allowance or 25%, and compares that with the full qualifying payment. At $1,600 per unit, a triplex counts at most $3,600 a month, which is below this example’s payment. At these assumptions this property would not pass; a lower price, higher appraised rents or a larger down payment would be needed. We check this test for every property before you make an offer.
Duplex reserve requirements depend on the underwriting path. Your lender may have additional requirements.
Source: HUD FHA Single Family Housing Policy Handbook 4000.1. Illustrative only; actual reserves are calculated from your verified payment.
Being a landlord
You become the landlord next door.
Owning a 2 to 4 unit property means finding and screening tenants under fair housing law, collecting rent, handling repairs and following Florida landlord-tenant rules, while living on site.
Direct Express Rentals can handle leasing, rent collection, maintenance coordination and owner reporting for the rented units, so you get the benefit without running it all yourself.
Next step
Model it for a real property.
Let's see what you would actually pay each month for a property you like.
Appointments are by phone, video or at our St. Petersburg office. Or call (727) 827-2884.
Multi-unit questions
Common questions about 2 to 4 unit FHA.
How much can I borrow with FHA on a 2 to 4 unit property in Pinellas County?
The 2026 FHA loan limits in Pinellas County are $693,050 for a duplex, $837,700 for a triplex and $1,041,125 for a fourplex (HUD; checked November 11, 2026). FHA allows as little as 3.5% down on an owner-occupied 2 to 4 unit home for borrowers who qualify. Limits change each year.
Do I have to be a first-time buyer?
No. First-time buyers often consider this path, but it is not a requirement. Occupancy and qualification rules apply.
Will rent cover my mortgage?
Not necessarily. Rents, vacancy and expenses vary. We will model the full payment with you before you decide.
Can I rent rooms to roommates instead?
Renting separate legal units is different from renting rooms. Ask us how each is treated.
Multi-unit consultation
Model a 2 to 4 unit purchase.
Share the property or area you are considering.
Prefer to talk? Call (727) 827-2884.
- You send your message
- It goes to the right team, with a reference number
- We follow up by phone or email
Want to talk to the broker?
Call or text Joe Cavaleri directly at (727) 686-0101. Office: (727) 827-2884, Monday–Friday, 9 AM–5 PM. Phones answered 24/7.